LBTT to September 2026: Scotland's Property Tax Take Is 3% Lower, and Gross ADS Is Down 6%
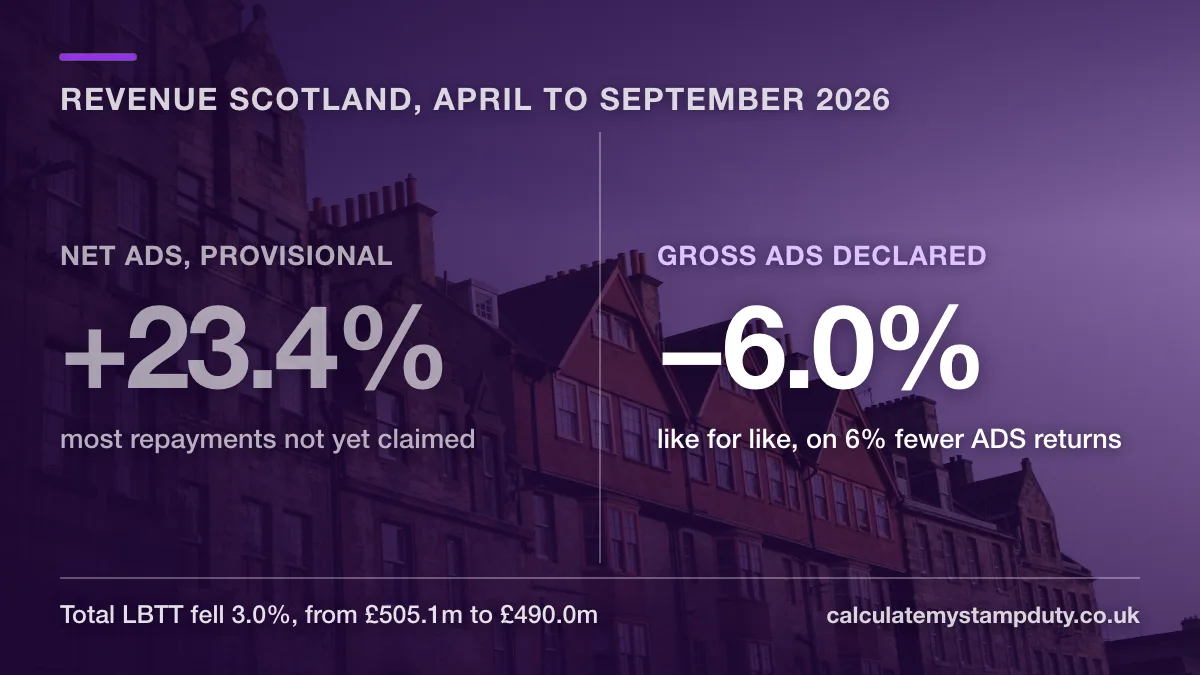
Revenue Scotland's 9 October release adds September data. Across the first six months of the financial year, total LBTT was £490.0m, 3.0% below the same months of 2025. Net ADS appears to have risen by 23%, but that reflects repayment claims not yet made on recent purchases. On a like-for-like basis, ADS declared was 6.0% lower.
Key Takeaways
- Revenue Scotland published LBTT statistics for September 2026 on 9 October 2026. They cover Scotland only and show tax declared on returns received in each month, not cash collected
- Residential LBTT excluding ADS was £47.7m in September 2026, 9% lower than August (£52.3m) and 12% lower than September 2025 (£54.1m)
- Gross ADS was £26.1m in September, 10% lower than September 2025 (£29.1m), and still the second highest September since ADS began in 2016
- For April to September 2026, total LBTT was £490.0m against £505.1m in the same months of 2025, a fall of 3.0%
- Residential LBTT excluding ADS was flat over the six months, £277.2m against £277.7m, while residential returns fell 4.5%. The fall in purchases was concentrated below £325,000, where little or no LBTT is due
- Net ADS for April to September looks 23.4% higher, at £130.2m against £105.5m. That comparison is distorted, because buyers replacing a main home have 36 months to sell the old one and reclaim ADS, and most claims on 2026 purchases have not been made yet
- Gross ADS, before any repayments, was £147.5m against £156.9m, down 6.0%, on 6.0% fewer returns with ADS due
- Non-residential LBTT excluding ADS was £82.6m against £121.8m, down 32.2%. Revenue Scotland notes that non-residential figures swing between months because of a small number of high-value transactions
- The release also revised 2025-26. Total LBTT for that year is now £965.2m, down from £968.4m in the August release, as further ADS repayments were claimed
- No LBTT rate or band changed between the two periods. Residential bands have been unchanged since 1 April 2021 and ADS has been 8% since 5 December 2024
September 2026 in Figures
Revenue Scotland published its monthly Land and Buildings Transaction Tax statistics on 9 October 2026, adding returns received in September. LBTT replaced stamp duty in Scotland in April 2015, so none of these figures include England, Wales or Northern Ireland. They measure the tax buyers declared on their returns, which is not the same as cash collected in the month.
| Scotland, LBTT | Sep 2025 | Aug 2026 | Sep 2026 | v Sep 2025 |
|---|---|---|---|---|
| Residential LBTT excluding ADS | £54.1m | £52.3m | £47.7m | -12% |
| Non-residential LBTT excluding ADS | £19.3m | £11.4m | £12.5m | -35% |
| Gross ADS declared | £29.1m | £26.4m | £26.1m | -10% |
| Residential returns | 9,910 | 9,050 | 9,010 | -9% |
| Returns with ADS due | 1,940 | 1,690 | 1,770 | -9% |
Residential LBTT fell further than the number of returns, and the difference sits at the top of the market. Purchases between £325,001 and £750,000 declared £29.5m in September against £33.1m a year earlier, and purchases over £750,000 declared £10.7m against £12.8m, on 130 returns rather than 160. Those two bands carry most residential LBTT, because the 10% and 12% rates apply to the slices of price above £325,000 and £750,000.
Gross ADS of £26.1m was 1% below August and 10% below September 2025. Revenue Scotland notes it was still the second highest September since ADS was introduced in 2016, behind only September 2025.
April to September: The Financial Year So Far
A single month can move for reasons that wash out over a longer period, particularly on the non-residential side. These are the first six months of 2026-27 against the same six months of 2025-26, summed from Revenue Scotland's monthly figures.
| April to September | 2025 | 2026 | Change |
|---|---|---|---|
| Residential returns | 56,000 | 53,490 | -4.5% |
| Residential LBTT excluding ADS | £277.7m | £277.2m | -0.2% |
| Gross ADS declared | £156.9m | £147.5m | -6.0% |
| Returns with ADS due | 10,830 | 10,180 | -6.0% |
| Non-residential LBTT excluding ADS | £121.8m | £82.6m | -32.2% |
| Total LBTT, including net ADS | £505.1m | £490.0m | -3.0% |
The total is lower by £15.1m. Almost all of the fall is non-residential: residential LBTT excluding ADS is within £0.5m of last year, and the non-residential line is £39.2m lower. The ADS line in the total is the net figure Revenue Scotland uses in its headline table, which brings its own complication, covered in the next section.
No LBTT rate or band changed between the two periods. The residential bands have been the same since 1 April 2021, the non-residential bands since 25 January 2019, and ADS has been 8% of the full price since 5 December 2024. The changes in the table are changes in what was bought, not in how it was taxed.
Why Net ADS Looks Higher When ADS Is Falling
The Additional Dwelling Supplement is charged at the point of purchase when the buyer already owns another residential property worth £40,000 or more. A buyer who is replacing a main home but has not yet sold the old one pays it too. For purchases with an effective date on or after 1 April 2024, that buyer can claim the ADS back from Revenue Scotland if the previous main residence is sold within 36 months.
Revenue Scotland records each repayment against the month of the original purchase. So the net ADS figure for any recent month starts high and falls as claims come in, which can be years after the purchase. It is one reason Revenue Scotland marks the statistics provisional for two years and revises them every month.
| ADS, April to September | 2025 | 2026 |
|---|---|---|
| Gross ADS declared | £156.9m | £147.5m |
| Repayments claimed so far | £51.3m (1,860 returns) | £17.1m (610 returns) |
| Net ADS | £105.5m | £130.2m |
The 2025 purchases have had a year longer for their owners to sell and claim, so £51.3m has already come off them. The 2026 purchases have had £17.1m claimed so far. Before any repayments, 2026 is lower: £147.5m of ADS against £156.9m, on 10,180 returns with ADS due against 10,830.
The revision is visible within a single month. The August release put net ADS for August 2026 at £25.6m. The September release puts the same month at £24.3m, because £1.3m more in repayments was claimed in the meantime.
A comparison to avoid
Net ADS for recent months should not be set against net ADS for older months, because the older months have had longer for repayments to arrive. Compare gross ADS, or the number of returns with ADS due, which are not reduced by later claims.
Where the Fall in Residential Purchases Was
Residential returns fell 4.5% over the six months while residential LBTT excluding ADS barely moved. Revenue Scotland's breakdown by total price shows why.
| Purchase price, April to September | Returns 2025 | Returns 2026 | Change | LBTT 2025 | LBTT 2026 |
|---|---|---|---|---|---|
| Up to £145,000 | 17,790 | 16,100 | -9.5% | £0.0m | £0.0m |
| £145,001 to £250,000 | 18,390 | 17,570 | -4.5% | £14.1m | £13.6m |
| £250,001 to £325,000 | 8,690 | 8,500 | -2.2% | £32.0m | £31.1m |
| £325,001 to £750,000 | 10,400 | 10,610 | +2.0% | £173.9m | £173.9m |
| Over £750,000 | 730 | 710 | -2.7% | £57.7m | £58.9m |
The fall in purchases was steepest at the bottom of the market. Purchases up to £145,000, which pay no LBTT, were down 9.5%, and purchases between £145,001 and £250,000 were down 4.5%. Purchases between £325,001 and £750,000 rose 2.0%, and that band alone accounts for 63% of residential LBTT excluding ADS. Fewer low-value purchases and slightly more mid-to-upper value ones left the tax total almost unchanged.
LBTT figures in this table exclude ADS and are allocated by the total price of the purchase. A purchase in the £325,001 to £750,000 band still pays 0%, 2% and 5% on the lower slices of its price. The table excludes leases, so its return counts are slightly below the headline residential total.
Non-Residential LBTT
Non-residential LBTT excluding ADS was £12.5m in September 2026, up 10% on August but 35% below September 2025. Over the six months it was £82.6m against £121.8m, a fall of 32.2%. Revenue Scotland cautions that non-residential revenues are highly variable between months because a small number of high-value transactions make up much of the total.
September shows that effect. There were 200 non-residential purchases over £350,000 in both September 2025 and September 2026. In 2025 they declared £17.9m. In 2026 they declared £10.6m. The number of large deals held, but the deals were smaller.
Activity on the other measures was steady. Non-residential conveyance returns were 630 in September, up 15% on 550 in August. New lease returns were 350, up from 300, and lease review returns, which include three, six and nine-year reviews, assignations and terminations, were 760 against 790.
Revisions to 2025-26
Because every month is revised as ADS repayments are claimed, the totals for 2025-26 have changed since the August release. On the same basis, summing the monthly figures for April 2025 to March 2026:
| 2025-26 (April to March) | August release | September release |
|---|---|---|
| Total LBTT | £968.4m | £965.2m |
| Residential, including net ADS | £730.5m | £727.1m |
| Net ADS, all property | £212.1m | £208.9m |
| Non-residential, including ADS | £237.9m | £237.9m |
The whole change is ADS repayments. Non-residential LBTT did not move. 2025-26 remains the highest year on this basis, although it will be revised down further as claims arrive: the same sum for 2024-25 is now £892.3m, so 2025-26 was 8.2% higher. We have updated the figures in our article on the Scotland LBTT review 2026, which quoted the August release.
What This Means for Buyers
Nothing in this release changes what any buyer pays. Residential LBTT is 0% up to £145,000, 2% from £145,001 to £250,000, 5% from £250,001 to £325,000, 10% from £325,001 to £750,000 and 12% above £750,000, and ADS is 8% of the full price. The full tables are on our current LBTT rates page.
ADS is the part most often missed by buyers from elsewhere in the UK. It applies if a buyer already owns a residential property worth £40,000 or more anywhere in the world and is not replacing a main home, so someone who owns a home in England and buys a second home in Scotland pays the 8% ADS rather than the English surcharge. Our guide to relocating between Scotland and England covers how the two systems interact.
For a buyer who pays ADS while waiting to sell a previous main home, the 36-month window matters more than these statistics. The repayment is not automatic. It has to be claimed from Revenue Scotland once the sale completes.
Annexe, land or an old home not sold yet?
These are the purchases where a standard calculator can get your stamp duty wrong. Get it checked before you exchange.
Frequently Asked Questions
How much LBTT was declared in September 2026?
Revenue Scotland's figures show £47.7m of residential LBTT excluding ADS, £12.5m of non-residential LBTT excluding ADS and £26.1m of gross ADS on returns received in September 2026. The figures are provisional and will be revised.
Is LBTT going up or down in 2026?
Down slightly. Total LBTT for April to September 2026 was £490.0m, 3.0% lower than £505.1m in the same months of 2025. Residential LBTT excluding ADS was flat, gross ADS fell 6.0% and non-residential LBTT excluding ADS fell 32.2%.
Why does net ADS look higher in 2026 when fewer buyers paid it?
Because repayments are recorded against the month of the original purchase, and they can arrive years later. £51.3m has been claimed back so far on April to September 2025 purchases, against £17.1m on April to September 2026 purchases. Before repayments, ADS was £147.5m in 2026 against £156.9m in 2025.
How long do you have to reclaim ADS in Scotland?
For purchases with an effective date on or after 1 April 2024, you can claim if you sell your previous main residence within 36 months of buying the new one, the previous property was your only or main residence at some point in the 36 months before the purchase, and you have lived in the new property as your only or main residence. Purchases before 1 April 2024 had an 18-month window.
Do these figures include England or Wales?
No. LBTT applies only in Scotland and is collected by Revenue Scotland. Stamp Duty Land Tax in England and Northern Ireland is collected by HMRC, and Land Transaction Tax in Wales by the Welsh Revenue Authority, and each publishes its own figures.
When is the next LBTT statistics release?
Revenue Scotland generally publishes on the second Friday of each month, which points to 13 November 2026 for October data. The confirmed date appears in the Scottish Government's calendar of forthcoming official statistics.
Calculate Your LBTT
These statistics describe the total declared across Scotland, not what any one purchase costs. For the LBTT and ADS on a specific Scottish purchase at current rates, use the calculator.
Use Scotland LBTT CalculatorSources
- Land and Buildings Transaction Tax (LBTT) monthly statistics: September 2026, Revenue Scotland, published 9 October 2026
- Monthly LBTT statistics tables, September 2026 (spreadsheet), Revenue Scotland
- Monthly LBTT statistics tables, August 2026 (spreadsheet), Revenue Scotland, for the revisions
- The Additional Dwelling Supplement (ADS), Revenue Scotland guidance
Figures are tax liabilities declared on LBTT returns received in each month, in £ millions, rounded by Revenue Scotland to the nearest £0.1m and the nearest 10 returns. Six-month and annual totals are our sums of the monthly figures, so they can differ from unrounded totals by a few tenths of a million. All months from April 2025 onwards are provisional. This article is not tax advice and is not affiliated with Revenue Scotland.
Reviewed by
Julie White
ACAStamp duty specialist since 1999Stamp Duty Land Tax Specialist
ACA and Tax Adviser with a career spanning nearly four decades, specialising in stamp duty planning and advisory work since 1999.